
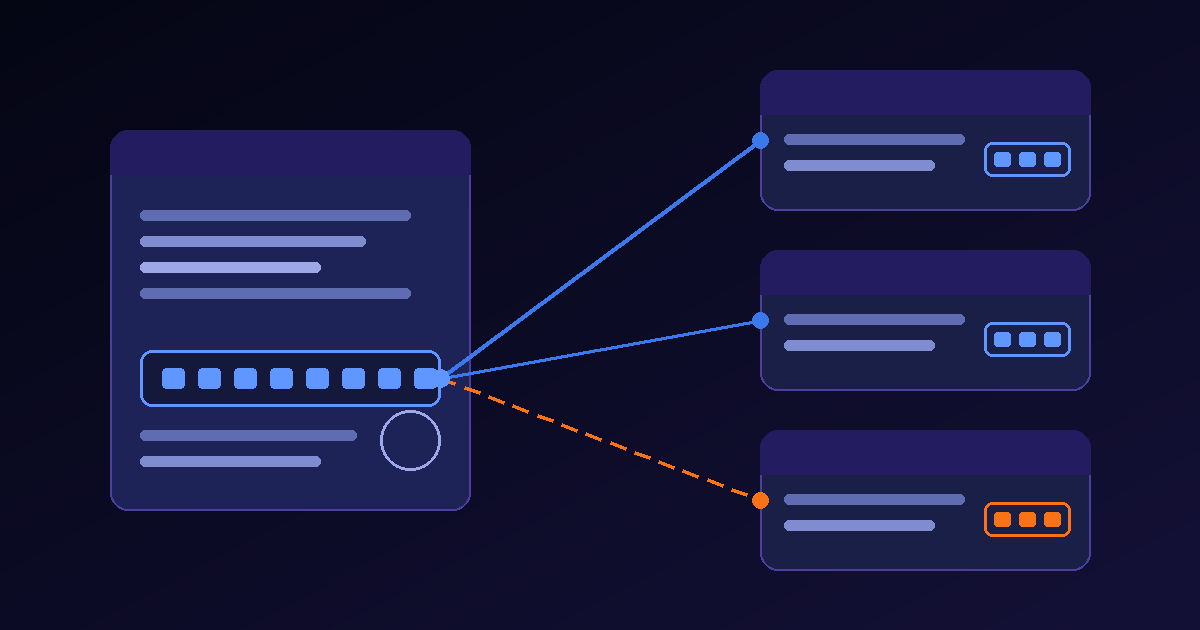
A marketplace that pays sellers has to know which business it is paying. The usual answer is a packet of documents uploaded at onboarding: a registration certificate, a tax form, a letter from the bank, an identity document for the person signing up, perhaps an invoice or a screenshot of a website. Each of them names the business. Most of them carry a number that the business was given by someone else — a company registry, a tax authority, a bank.
Know-your-business review is often described as checking those documents. In practice, most of the work is checking them against each other. The certificate says a company with a certain name holds a certain registration number. The tax form says the same number, or a different one, belongs to a name that may or may not be the same. The bank letter says an account is held by a name that should be one of those two. A reviewer who reads each document alone can find nothing wrong with any of them and still approve a seller whose papers describe three different businesses.
This piece describes how to extract a KYB packet so that the identifiers become the join key between documents, how to treat names that legitimately differ, and how to route the disagreements that remain. It does not cover sanctions screening, registry lookups or a verdict on whether a seller is honest. Those decisions sit downstream, and they are easier to make when the packet has been reconciled first.
The number is the key, the name is the claim
Start with what the issuing body actually records. Companies House describes the certificate of incorporation for a UK company as stating the name and registered number of the company, the date of incorporation, whether it is limited by shares or by guarantee, whether it is private or public, and where its registered office is. Of those, the number is the field built to stay fixed. Names change: a company can choose a new one, and it can be ordered to change its name when that name is too like another on the index or gives a misleading indication of its activities.
That asymmetry should shape the matching. The registration number is the identifier, so the first comparison is number against number. The name is a claim attached to that number at a point in time, so the second comparison is name against name, with the document date beside it. A certificate issued before a change of name will carry the former name and the same number. A recent invoice will carry the current name and, often, the same number. Neither document is wrong, and a matcher that compares names first will report a mismatch where none exists.
The reverse failure is worse. Companies House notes that a name may be too like another if it differs by only a few characters, signs, symbols or punctuation. Two different companies can therefore have names that a loose string comparison would call equal. If the matcher accepts a name as close enough without checking the number, it can join documents from two separate businesses into one seller record.
What each document is able to say
The documents in a KYB packet are not interchangeable. Each one was issued by a different party for a different purpose, and each can establish some things and not others. Before comparing fields, the extraction should record which fields each document is in a position to assert.
| Document | Issued by | Identifier fields | Name fields | What it cannot establish alone |
|---|---|---|---|---|
| Certificate of incorporation | Company registry | Registered number, date of incorporation | Registered name at the date of issue | That the name is still current, or who owns or runs the company today |
| Form W-9 | The payee, on an IRS form | TIN (EIN or SSN) | Line 1 name, line 2 business or disregarded entity name | That the name and TIN combination matches IRS records |
| Bank account letter | The bank | Account and routing details | Account holder name | That the holder is the registered company rather than a related one |
| Invoice or letterhead | The business itself | Registered number, if shown | Registered name, trading name | Anything an issuer could not also print about itself |
| Ownership declaration | The applicant | None of its own | Owners and controllers, by person | That the people named are the full set |
The last column matters more than the others. A bank letter is good evidence that an account exists and who the bank thinks holds it. It is weak evidence of a registration number, because the bank was not asked to certify one. An invoice printed by the seller is weak evidence of anything the seller is being checked for. Extracting every field from every document is fine; giving every field the same weight is not.
Names that legitimately differ
Most name disagreements in a clean packet are explainable, and the extraction should explain them rather than flag them. Three patterns account for many of them.
The first is the trading name. Companies House defines a business name, for a limited company, as any name under which it carries on business that is not its registered name. A shop can trade as one name while the company that owns it is registered under another. The invoice and the storefront show the trading name; the certificate shows the registered one. The two are linked by the number, or by the registered name printed alongside the trading name, not by any similarity between the strings.
The second is the disregarded entity on a US tax form. The IRS instructions for requesters of Form W-9 say that, for proper processing, a disregarded entity reports its owner’s name on line 1 and its own name on line 2. A single-member LLC that sells on a marketplace may therefore submit a W-9 whose first line names a person or a parent company. The TIN on that form belongs to the line 1 name. Comparing line 1 to the LLC name on a state filing will fail every time, and correctly so; the comparison that should succeed is line 2 to the LLC name, with line 1 recorded as the tax owner.
The third is formatting. Legal suffixes are abbreviated or spelled out, punctuation is dropped, letters are capitalised differently, and an ampersand becomes a word. Normalising these is reasonable, but only for an agreed list of transformations, and the extraction should keep the original string beside the normalised one. Anything beyond that list is a difference for a person to look at, given how small the difference between two registered names can be.
Field, source, comparison, divergence, routing
The table below shows the shape of the output for a fictional seller, Northfield Supply Ltd, applying to sell on a marketplace. The packet contains a UK certificate of incorporation, a bank letter, two invoices, a W-9 for a US subsidiary that will receive US payouts, and an ownership declaration.
| Field | Source | Comparison | Divergence | Routing |
|---|---|---|---|---|
| Registered number | Certificate, p. 1: 09876543 | Invoice A footer: 09876543; invoice B footer: 09876534 | Invoice B transposes two digits | Flag; ask which number is printed on current stationery |
| Registered name | Certificate, p. 1, issued 2019-03-04: Northfield Trading Ltd | Invoices: Northfield Supply Ltd, same number | Name differs; number agrees | Request the change-of-name record; hold the name match until it arrives |
| Trading name | Invoice A header: Northfield Home | Footer of the same invoice: Northfield Supply Ltd, 09876543 | None; trading name linked to registered name on the same page | Record as trading name of the seller |
| Bank account holder | Bank letter dated 2026-10-02: Northfield Holdings Ltd | Registered name: Northfield Supply Ltd | Account held by a different company name | Route to review: payouts to a related entity need a decision, not a match |
| US tax owner | W-9 line 1: Northfield Supply Ltd; line 2: Northfield US LLC | State filing: Northfield US LLC | None; line 2 matches the LLC, line 1 is the owner as the instructions direct | Record the LLC as a disregarded entity of the seller |
| Controlling person | Ownership declaration: one director listed | Bank letter signatory: a second named person | Signatory not on the declaration | Ask whether the declaration is complete |
Three things in that table do work a document-by-document review would miss. The transposed digits on invoice B are invisible unless invoice B is compared against the certificate; read alone, it is a well-formed invoice. The name row does not fail the seller; it holds the comparison open and asks for the document that would close it, because the number already agrees. And the bank row does not resolve anything. Whether a marketplace pays a related company is a policy question, and the extraction’s job is to put the fact in front of the person who owns that policy.
The holder on the bank letter
The bank letter deserves its own attention because it is where money goes. Its account holder name is the bank’s record, not the applicant’s, and it often follows the bank’s formatting: truncated to a field length, in capitals, with suffixes dropped. A strict comparison will flag a correct letter. A loose one will pass a letter for a parent, a subsidiary or an unrelated company with a similar name.
The workable middle is to compare the holder name against every name the packet has already tied to the registration number — registered name, former names supported by a record, trading names linked on the same page — and to report which one it matched and how. If it matches none of them, the result is a divergence with both strings and the letter’s date, not a similarity score. A score invites someone to set a threshold, and a threshold is exactly where two too-like names slip through together.
Who the evidence is about
A business is also a set of people. For financial institutions in the United States, the customer due diligence rule at 31 CFR 1010.230 requires covered institutions to identify and verify the beneficial owners of legal entity customers. It defines them in two prongs: each individual who directly or indirectly owns 25 percent or more of the equity interests, and a single individual with significant responsibility to control, manage or direct the entity, such as an executive officer.
A marketplace may or may not be subject to that rule; its payment partner usually is. Either way, the rule contains a sentence that describes the value of cross-document checking well. A covered institution may rely on the information supplied by the legal entity customer about its beneficial owners, provided it has no knowledge of facts that would reasonably call the reliability of that information into question. A signatory on the bank letter who is missing from the ownership declaration is such a fact. So is a director named on one document and absent from another. The extraction does not decide what those facts mean. It makes sure they are known.
Dates decide which document is current
Every identity field in the packet was true on some date. The certificate is true as of its issue date. The bank letter is true as of the day it was written. The ownership declaration is true as of the day it was signed, and the invoices as of the day they were printed. When two documents disagree, the dates usually say whether the disagreement is a change or a contradiction.
The extraction should therefore carry the date of every value it reports and order the evidence for each field by date. A name on a 2019 certificate and a different name on a 2026 invoice, with the same number, is a sequence to be documented. Two different names on documents dated the same month is a contradiction to be routed. Without the dates, both look the same.
Not the travel rule file, not the onboarding agent
Two neighbouring pieces cover adjacent ground. Travel Rule counterparty due diligence is about checking another virtual asset service provider before customer data is sent to it, including comparing an extracted FinCEN registration number against the published registry. Here the business is the applicant, the documents are its own, and the comparison is between them. The 2026 autonomy bar uses a vendor onboarding packet to show how an agent differs from a script. This piece is the matching layer that kind of agent needs underneath it: which field joins which document, and what to do when it does not.
Collecting the documents is a third problem. The first mile is a product describes how a request that needs one identity document per beneficial owner expands into as many slots as there are owners. The output of that portal is the input here.
What the extraction does not decide
The extraction reads what the documents say and compares them. It does not confirm that a registration number exists in a registry, unless a registry lookup is configured as a separate step with its own evidence. It does not confirm that a name and TIN match IRS records; the IRS offers TIN matching as an e-service to payers who are required to file information returns, and that check belongs to them. It does not screen names against sanctions lists, and it does not declare a seller fraudulent. A divergence is a reason to ask a question, and the person who asks it should have the pages in front of them.
What the extraction has to deliver
- Every identifier and name with its document, page, issuer and date, and the original string beside any normalised form.
- The registration number as the join key, with each document’s number compared against the registry document’s.
- Names matched against the set already tied to that number, with the rule that linked each one: former name, trading name, disregarded entity.
- Divergences stated as both values with their pages, never as a similarity score.
- People named anywhere in the packet listed against the ownership declaration, with the ones that appear only elsewhere marked.
- A routing reason for every open item, so the reviewer knows which question to ask.
Keep the number and its pages together
A KYB packet is persuasive one document at a time. That is what makes it easy to approve and hard to trust. The useful unit of review is not the certificate or the bank letter but the identifier that runs through all of them, with every page that mentions it and every name attached to it on that date. When that thread holds, a reviewer can approve quickly and say why. When it breaks, the break is the first thing they see.
Sources
- Incorporation and names (Companies House guidance, updated 19 October 2026) — what a certificate of incorporation states, ‘too like’ names that differ by a few characters, orders to change a name, and business names that are not a company’s registered name.
- Instructions for the Requester of Form W-9 (03/2024) — the owner’s name on line 1 and the disregarded entity’s name on line 2, and TIN matching for payers who file information returns.
- 31 CFR 1010.230, Beneficial ownership requirements for legal entity customers (eCFR) — the ownership and control prongs of the beneficial owner definition, and reliance on customer-supplied information absent facts that call it into question.