
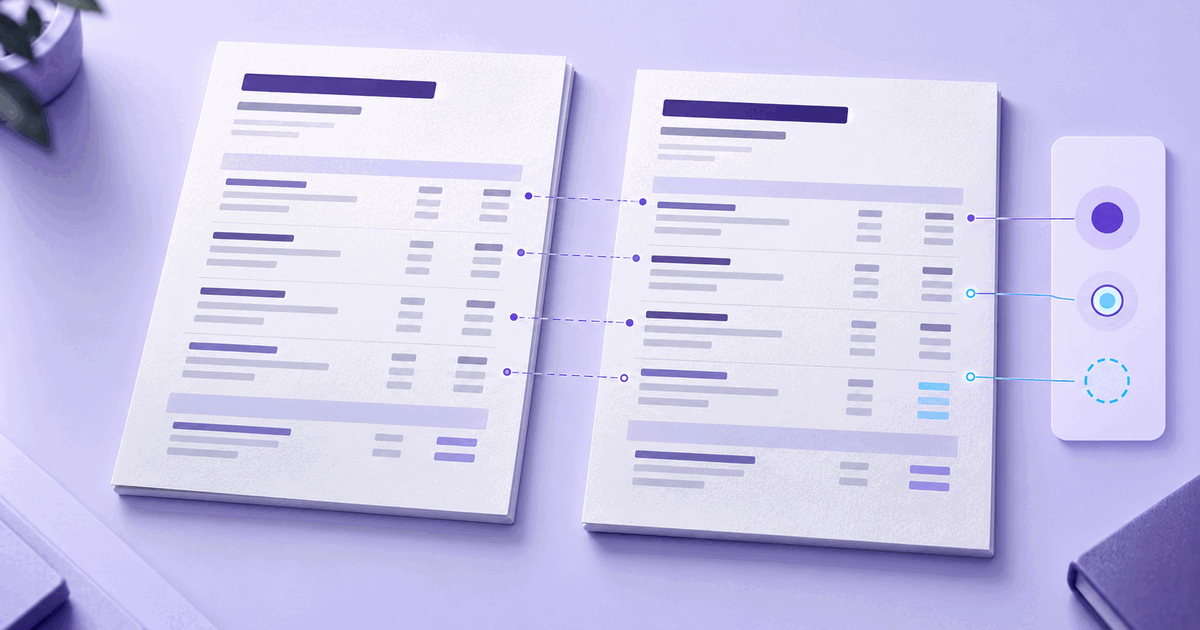
The useful comparison is not “did this line go up?” It is “what rule governs this charge, what evidence puts it there, and what changed between the estimate and closing?” Under the TILA-RESPA Integrated Disclosure (TRID) rule, the answer depends on the charge’s category and the facts behind it.
Start with the same transaction and the right versions
The Loan Estimate (LE) is an early good-faith estimate. The Closing Disclosure (CD) gives the final terms and costs. Build a comparison from the most recent LE that applies and the CD delivered for consummation; retain each document’s issue date, version and page. A corrected form should not silently overwrite the version that came before it.
Before comparing amounts, align the underlying service. Normalize labels only to propose a match, then preserve the printed descriptions, provider, amount, estimate date and source location on both sides. “Title services” on one form may cover several services on the other; a similar label alone does not establish that two rows are the same charge.
Classify each charge before testing its change
For each LE charge, capture the service, the disclosed provider or provider category, whether the consumer was permitted to shop, the amount and any written provider-list context. Link it to a CD charge only when the service and transaction facts support that match. Then classify it under 12 CFR 1026.19(e)(3):
- Zero tolerance: charges paid to the creditor, mortgage broker or their affiliates; charges for a service the consumer was not permitted to shop for; and transfer taxes generally cannot increase above the applicable estimate, subject to the rule’s limited provisions.
- 10% aggregate tolerance: eligible charges for services the consumer was permitted to shop for, when the consumer selects a provider from the written list, plus recording fees. The limit applies to the sum of applicable charges, not separately to every row.
- Permitted to vary: specified charges such as prepaid interest, property-insurance premiums, initial escrow deposits, certain services when the consumer selects a provider outside the written list, and services not required by the creditor. Keep the exact regulatory conditions with the classification.
These labels are a rule-based grouping, not an amount-based guess. The same service name can land differently when the provider relationship or shopping facts differ. If those facts are absent, preserve the uncertainty for review rather than assigning a bucket from the dollar movement.
The 10% test is a pooled calculation
Suppose eligible recording and third-party shopping charges total $1,000 on the applicable LE. On the CD, one eligible fee rises by $40 and another falls by $20. The comparison is $1,020 against the $1,000 aggregate baseline: the pool is up 2%, even though one individual line rose 40%. A per-line alert would misstate the rule.
The converse matters too. A single line can be unchanged while the eligible group, taken together, exceeds its baseline by more than 10%. Keep the included rows, amounts and sum visible so a reviewer can reproduce the test. Do not place charges from the zero-tolerance or permitted-to-vary categories into this pool.
Preserve the baseline and any permitted reset
A changed estimate does not automatically reset every tolerance. Section 1026.19(e)(3)(iv) permits a revised estimate for specified changed circumstances, consumer-requested changes, rate locks, certain delayed settlements involving new construction, and other listed events. The creditor must meet the rule’s timing and disclosure conditions. Record the stated event, when it became known, the revised LE date and the specific charges affected.
Compare the CD to the applicable disclosed baseline for each charge, not simply to the first LE or the latest file in a folder. Keep both original and revised values and the reason a revised estimate applies. Where no qualifying event and timely disclosure can be evidenced, do not treat a later number as a valid reset.
Turn the comparison into an audit trail
A useful reconciliation record ties each conclusion to its inputs:
- Identity: LE and CD versions, dates, loan and property identifiers, and page references.
- Charge match: printed descriptions, service, provider, consumer shopping status and evidence used to link rows.
- Bucket: zero, 10% aggregate or permitted to vary, with the facts supporting that classification.
- Calculation: applicable baseline, CD amount, included 10% pool rows and aggregate result.
- Change evidence: any claimed changed circumstance or other permitted event, dated notice and affected amounts.
- Disposition: within tolerance, potential excess requiring review, or not measurable from the documents provided.
Keep OCR output linked to its page and region, and distinguish a blank or unreadable field from a confirmed zero. Extraction can organize the evidence and perform a reproducible arithmetic comparison; a qualified human should determine how the rule applies to the transaction.
Keep the two reviews distinct
This article compares the LE with the CD to organize TRID tolerance analysis. A separate closing review may compare the CD with the title commitment to connect payoffs, vesting, requirements and recorded exceptions. That is the scope of the Closing Disclosure and title commitment reconciliation; it does not answer whether an LE charge fits a tolerance bucket.
For the governing text, see the CFPB’s 12 CFR 1026.19(e)(3), its consumer explanation of final mortgage-cost changes, and the Closing Disclosure guide. This overview is educational and does not provide legal advice or decide whether a specific charge complies.