
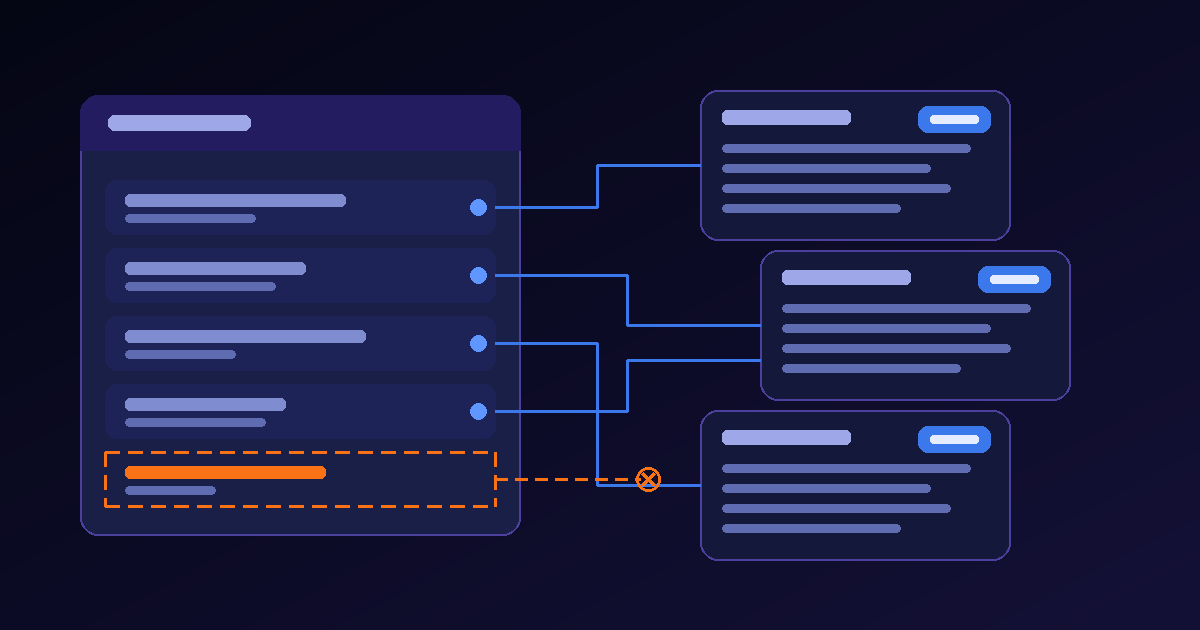
Every review or audit engagement starts with a request list. The client answers it the way clients usually do: a shared folder, a zip file, or a portal upload with forty PDFs whose names say scan_0012.pdf, Dec stmts FINAL, and loan docs. The staff accountant then spends hours opening each file to decide which request it answers, whether it covers the right period, and where the figure the workpaper needs actually sits.
That work produces the index. It is also the part of the engagement that rarely bills well, because it is clerical in shape and judgment-heavy in detail. Audit workpaper indexing is the step that turns a pile of client documents into a structure a reviewer can follow: each number in a workpaper points to a request, each request points to a document, and each document points to a period and a page.
A folder of PDFs is not an index
A folder answers one question: what did the client send? An index answers a different one: which requests are satisfied, by what evidence, and which are still open? The difference matters at review time. A manager checking a cash lead sheet does not want to find “the bank stuff” somewhere in a folder. They want the December statement for the operating account, page 3, where the closing balance is printed.
The file name is the weakest link in that chain. Clients rename, merge, and split documents freely. One PDF may hold twelve monthly statements; another may hold a single page of a lease. An index built on file names breaks the moment a client resends a corrected version under a new name. An index built on document type, period, and page survives it.
The index has five columns
The minimum structure is small. Each row links a request to the evidence that answers it, and the status column says whether the answer is complete. The example below is fictional, for a calendar-year client with a December 31 year-end.
| Request | Document | Period | Page | Status |
|---|---|---|---|---|
| Bank statements, operating account | Bank statement, account ending 4417 | December 2025 | 3 of 6 | Received |
| Bank statements, payroll account | Bank statement, account ending 0982 | November 2025 | 1 of 4 | Wrong period |
| Loan agreement and year-end balance | Lender balance confirmation | As of December 31, 2025 | 1 of 1 | Received |
| Fixed asset additions over threshold | Vendor invoices, 3 of 4 listed additions | Fiscal 2025 | Various | Partial |
| Lease agreement, warehouse | — | — | — | Missing |
Two of the five rows are done. The other three are the reason the index exists. The payroll statement arrived but covers November, not December. One of four fixed asset invoices is absent. The warehouse lease never arrived at all. A folder view shows none of that; it shows a set of files that all look like they answer something.
The period breaks first
The most common mismatch is not the wrong document type. It is the right document type for the wrong period. A November statement looks identical to a December statement except for a date range near the top of page 1. A prior-year tax return looks identical to the current one except for the year printed in the header. A balance confirmation dated January 15 is not a confirmation as of December 31 unless it says so.
That is why the period belongs in its own column, extracted from the document itself, not inferred from the file name or the upload date. When the client's fiscal year does not end in December, the check gets harder: “year-end” means a different month for each entity, and the request list has to carry that date explicitly. An extraction that reads the statement period and compares it with the requested period catches the November payroll statement at intake, while the client still remembers where the December one is.
A page reference, not just a file
Pointing a workpaper figure at a file is better than nothing. Pointing it at a page is what lets a reviewer verify it in seconds. Bank statement bundles, loan packages, and year-end confirmations often arrive as multi-document PDFs; the figure that matters sits on one page of one document inside the bundle.
The same idea appears in lending, where a single loan PDF has to be indexed against a checklist by document type and page range; we covered that version in indexing a mortgage loan file. In an engagement, the checklist is the request list, and the page reference is what lets a tickmark on a lead sheet lead back to the exact line in the source.
The missing item is the useful output
An index that lists only what arrived is a table of contents. The engagement team needs the opposite view: what is still open, and why. Each row should end in one of a short set of states, and each state should carry a next step.
- Received — the document matches the request, the period, and the entity; the page reference is recorded.
- Wrong period — the document type matches, but the period does not; ask for the correct month or year, not the whole request again.
- Partial — some of the items the request lists are present; name the ones that are not.
- Missing — nothing in the upload answers the request; it goes back to the client with the original wording.
- Needs review — the document might answer the request, but the match is uncertain; a person decides.
Returning only the gap to the client, with the specific period or item that is missing, is faster for both sides than resending the full request list. It is the same principle as asking for the missing piece instead of restarting the workflow.
What to capture for each document
The index is only as good as the fields behind it. For each document in the upload, a reviewable index keeps:
- Document type — bank statement, lender confirmation, invoice, lease, tax return, with the evidence that classified it.
- Entity and account — the legal entity, and for statements the account identifier, so multi-entity clients do not cross wires.
- Period — the start and end dates or the as-of date printed on the document, compared with the requested period.
- Page range — where the document starts and ends inside the uploaded file, plus the page that holds the key figure.
- Request link and status — which request the document answers, the status, and who confirmed the match.
With those fields, a corrected document from the client replaces one row instead of invalidating the index. The reviewer can still see the earlier version, when it was superseded, and why.
Where document AI stops
Document AI can classify the documents in a client upload, read their periods and identifiers, find page ranges, and propose which request each one answers, with a source reference for every field. Cogneris describes this workflow on its accounting firm solutions page, alongside the tax-software integrations that use the same extracted data.
What it does not do is decide whether the evidence is sufficient. Whether a confirmation supports a balance, whether a missing invoice matters, and whether a workpaper is ready for sign-off are judgments that belong to the engagement team and the standards it works under. The index makes those judgments faster to reach and easier to review; it does not replace them. This article is an operational example, not audit or accounting advice.