
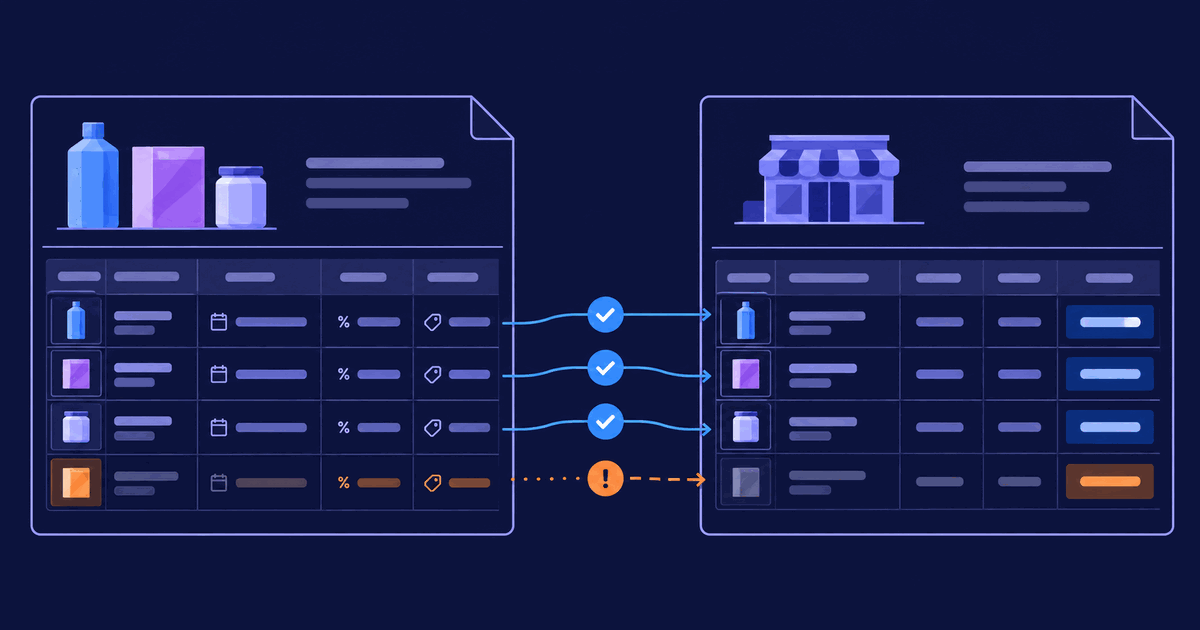
A trade promotion rebate deduction can look like one line on a remittance, but the terms that support it are usually spread across a sell sheet or promotion agreement. The retailer’s amount only makes sense beside the offer it refers to: the active dates, eligible products, calculation base and any cap.
That makes this a document-matching problem before it is a posting decision. A deduction label such as “promo allowance” is not enough to show which offer applies, whether the period is right or how the amount was calculated. The source documents and the retailer’s claim need to stay visible together.
The sell sheet describes the offer
A supplier sell sheet or promotion calendar can carry several offers at once. One may apply to a defined period, another to a list of SKUs, and a third to a stated percentage or amount. A retailer’s deduction may use the same short label for each. The job is to capture the terms that distinguish one offer from the next, rather than treating every rebate as a single percentage.
Cogneris’s retail document workflow describes extracting supplier sell sheets and promotion calendars into merchandising-ready records while preserving effective dates and rebate terms. For a reconciliation, those fields become the evidence to compare against the retailer’s deduction.
| Promotion term | What to preserve | Why it matters |
|---|---|---|
| Effective period | Start and end dates as printed, plus the source page | A deduction outside the stated window needs a person to check whether another offer or amendment applies |
| Eligible products | SKU identifiers and any inclusion or exclusion notes | A matching promotion name does not prove every product qualified |
| Calculation base | The stated unit, sales or purchase basis and its scope | The same percentage can produce different amounts when the base changes |
| Rate and cap | Percentage or fixed amount, thresholds and maximum value | The claimed amount can be compared with the terms actually present in the agreement |
Compare the claim with each term
Consider a hypothetical offer: 10% on eligible purchases of one SKU during April, capped at $180. If the documented eligible base is $2,000, the percentage yields $200, but the stated cap limits the example amount to $180. A retailer deduction of $200 would leave a $20 difference to investigate. The numbers are illustrative; the signed offer and the retailer’s supporting detail determine the real comparison.
The useful record shows both sides. Keep the amount and reference from the deduction, then link them to the promotion document and the exact fields used for the comparison. If the base, product or date cannot be established from the source, mark it as missing. Do not fill the gap with a default or infer a term from a similar promotion.
| Deduction evidence | Promotion evidence | Result to record |
|---|---|---|
| Retailer, remittance reference and claimed amount | Offer identifier, source version and page citation | Which documents were compared |
| Claimed period and product references | Effective dates and eligible SKUs | Matched, outside the period, or product not listed |
| Claimed calculation or quantity detail | Calculation base, rate and cap | Amount explained by terms, difference found, or evidence missing |
Keep exceptions explainable
A mismatch is a reason to review, not a verdict about the retailer or supplier. The source may be incomplete, a revised offer may exist, or the deduction may refer to a different promotion. Keep those possibilities open until the relevant document is found.
- Dates do not overlap — retain the printed dates and ask whether an amendment or another offer applies.
- Product is not listed — preserve the SKU as received and route the item for confirmation.
- Base is unclear — keep the claimed amount separate from the calculated amount and request the missing basis.
- Amount exceeds the stated cap — show the arithmetic and the source location for the cap, then route the difference for review.
- Two offers could fit — retain both candidates and the reason each might apply instead of silently choosing one.
For each exception, a reviewer should be able to open the source page and see the term behind the flag. The record can say “period not evidenced” or “claimed amount exceeds the captured cap”; it should not decide that a deduction is unauthorized or change an account balance by itself.
A rebate credit note is a related record
A supplier may issue a credit note for a volume rebate or year-end adjustment. As our credit memo guide explains, a credit can apply across a period and may not name one invoice. That credit note is evidence of a supplier-side adjustment; it does not automatically establish which retailer deduction it settles. Keep the period, amount and references from the credit, and link it to a deduction only when the supporting records show the relationship.
This distinction prevents two different documents from being collapsed into one total. A promotion agreement says what terms were offered. A retailer remittance says what was deducted. A supplier credit says what the supplier credited. Each has its own source, date and amount.
Make the comparison reviewable
A useful reconciliation preserves the original values, their document locations and the comparison rule applied. It also makes the unresolved part explicit: missing evidence, a date mismatch, an unlisted SKU, an unclear base or a difference against a cap. The next person can then review the same facts without reconstructing the offer from email or spreadsheet notes.
The goal is not to guess which side is right. It is to make the trade promotion rebate deduction traceable to the sell sheet, show where the terms agree or differ, and leave contract interpretation and posting policy with the people who own them.